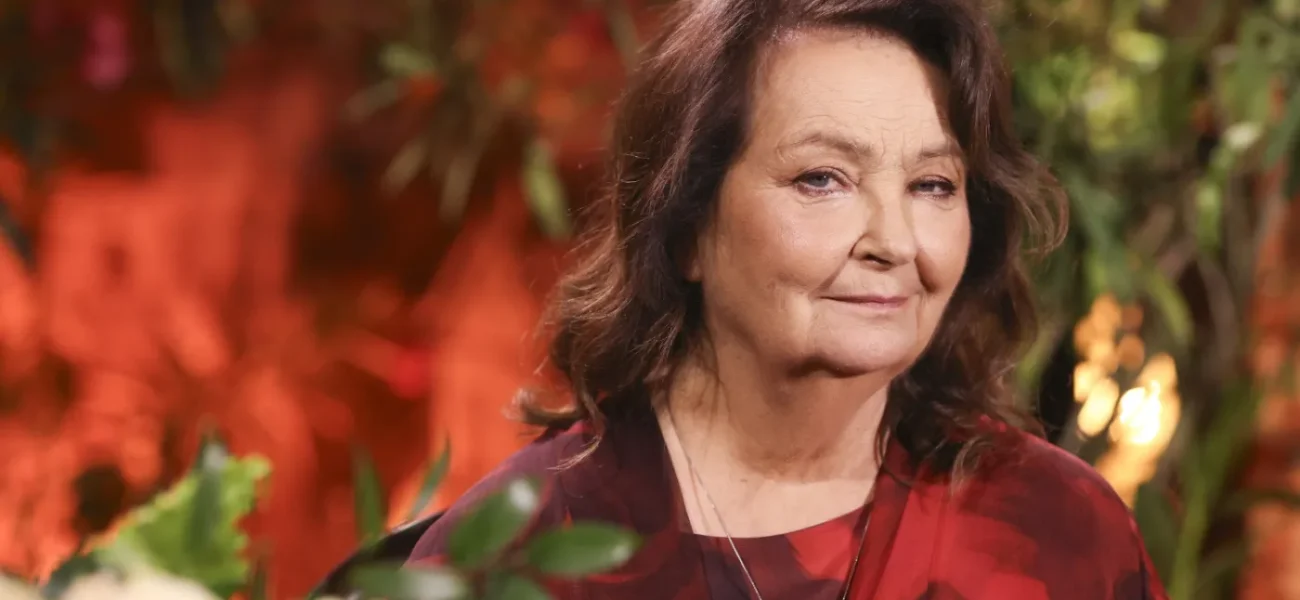
Anna Dymna Reveals What She Did With Her Pension: The Difference Is Significant
Actress Anna Dymna worked for 10 years past retirement age without drawing benefits, revealing that her current pension now exceeds her previous salary. Anna Dymna Worked 10 Years Past Retirement Age...
Actress Anna Dymna worked for 10 years past retirement age without drawing benefits, revealing that her current pension now exceeds her previous salary.
Table Of Content
Anna Dymna Worked 10 Years Past Retirement Age
Anna Dymna reached retirement age but did not end her professional activity, working for another 10 years without collecting benefits. Today, she admits that the amount of her pension exceeds her previous salary.
Now 75 years old, the actress remains professionally active. Connected to the Stary Teatr in Krakow for decades, she chose not to claim her pension immediately upon reaching the statutory retirement age, continuing to work without combining her wages with Social Insurance Institution (ZUS) payments for the next decade.
In an interview with Aleksandra Pajewska of Plotek, Dymna stated that she knew the rules allowing the postponement of retirement. She emphasized that the decision brought her a measurable financial effect, noting that her current pension is higher than her earlier earnings.
Dymna explained that she did not start collecting benefits after reaching retirement age, stressing that a pension is an entitlement rather than an obligation to stop working. Her case aligns with the rules of the universal pension system.
How ZUS Calculates Increased Pensions for Delayed Claims
In Poland, the universal retirement age is 60 for women and 65 for men. Reaching it means the right to apply for a pension from ZUS, but the insured person is not forced to do so immediately and can continue employment to file the application later. ZUS points out that postponing this decision can significantly increase the monthly benefit.
The mechanism of increasing the benefit stems directly from how pensions are calculated in Poland. ZUS considers indexed contributions accumulated in the insured’s account, funds recorded in the sub-account, and initial capital, which are then divided by the average further life expectancy expressed in months.
The later an insured person retires, the more favorable both equation elements become, as capital continues to grow through subsequent contributions and indexation while the projected benefit collection period shortens.
ZUS indicated in September 2025 that every additional year of professional activity after reaching retirement age can increase the benefit by up to a dozen or so percent, though the exact amount depends on accumulated capital, earnings, contributions, indexation, and the age at application.
According to ZUS calculations, shortening the anticipated benefit collection period means that for a 60-year-old, a one-year deferral increases the pension by about 3.7 percent, and five years by over a fifth. For a 65-year-old, the values are about 4.1 percent after a year and 23.4 percent after five years, alongside contributions paid during further work and indexation.
ZUS Examples and Financial Trade-Offs
The institution provides examples showing the scale of potential differences. A man born in 1959 who could have started drawing a pension in September 2024 but worked an additional year obtained a simulated benefit higher by 19.1 percent, rising from 3,882 PLN to 4,623 PLN monthly.
At the same time, ZUS notes that postponing retirement means giving up earlier payouts. In this example, the value of 12 unpaid benefits would be recovered after about 6.5 years of collecting the higher pension.
An even greater difference appeared in another calculation for a man born in 1955 who delayed retirement by five years, increasing his benefit from 2,477 PLN to 5,147 PLN. Here, the value of five years of previously unpaid pensions would be recovered after about 7.5 years of drawing the new amount.
This does not mean postponing retirement is automatically the best solution for everyone, as it depends on health, earnings, accumulated capital, and individual plans. ZUS therefore provides a pension calculator and advisory consultations.
Growing Trends of Seniors Working Past Retirement Age
Further professional activity among seniors is not a marginal phenomenon in Poland. According to ZUS data at the end of June 2025, about 1.2 million working people of retirement age were registered for health insurance, including both those already drawing pensions and those who postponed their applications.
Out of this group, 989.9 thousand people paid retirement insurance contributions. By the end of 2024, 872.6 thousand people with established retirement rights were working, which was 2.2 percent more than the previous year.
Over a decade from 2015 to 2024, the number of working pensioners increased by more than half, making up 13.7 percent of all pensioners at the end of 2024, with women comprising 58.1 percent of this majority.
The average retirement age in 2024 was 62.7 years, with 60.6 years for women and 65.1 years for men, showing that a large portion of insured individuals still apply for benefits relatively soon after reaching the statutory age.
Tax Relief and Non-Financial Benefits for Working Seniors
People who continue working after reaching the universal retirement age without drawing benefits can additionally use the tax relief for working seniors. In 2026, the PIT-0 scheme covers revenues up to 85,528 PLN annually if statutory conditions are met.
The Ministry of Finance indicates that women over 60 and men over 65 can use this relief if they do not collect a pension despite acquiring rights and earn income covered by the exemption, applying to employment contracts, specific mandate contracts, and business activities.
Filing a prior pension application is not required to use this solution, provided the individual does not draw benefits. The Ministry of Finance also notes that taxpayers taxed according to the tax scale can additionally benefit from the tax-free amount of 30,000 PLN.
Dymna did not reveal the exact amount of her benefit, meaning there is no basis to estimate what she receives from ZUS precisely. However, her own account confirms that her pension exceeds the salary she earned before transitioning to the benefit.
The actress noted that she did not plan a decade of extra work solely to boost her future pension, continuing her professional activity simply because she wanted to work. Financially, however, the result aligned with the ZUS system mechanism where later benefit collection leads to a significant increase in monthly amounts.
Dymna remains tied to social work through the “Mimo Wszystko” Foundation, which she established over two decades ago to help people with disabilities, emphasizing that professional and social activity is just as vital to her as the financial side of delayed retirement.