Ministry of Finance Tightens Rules on Family Foundations with Tax Overhaul
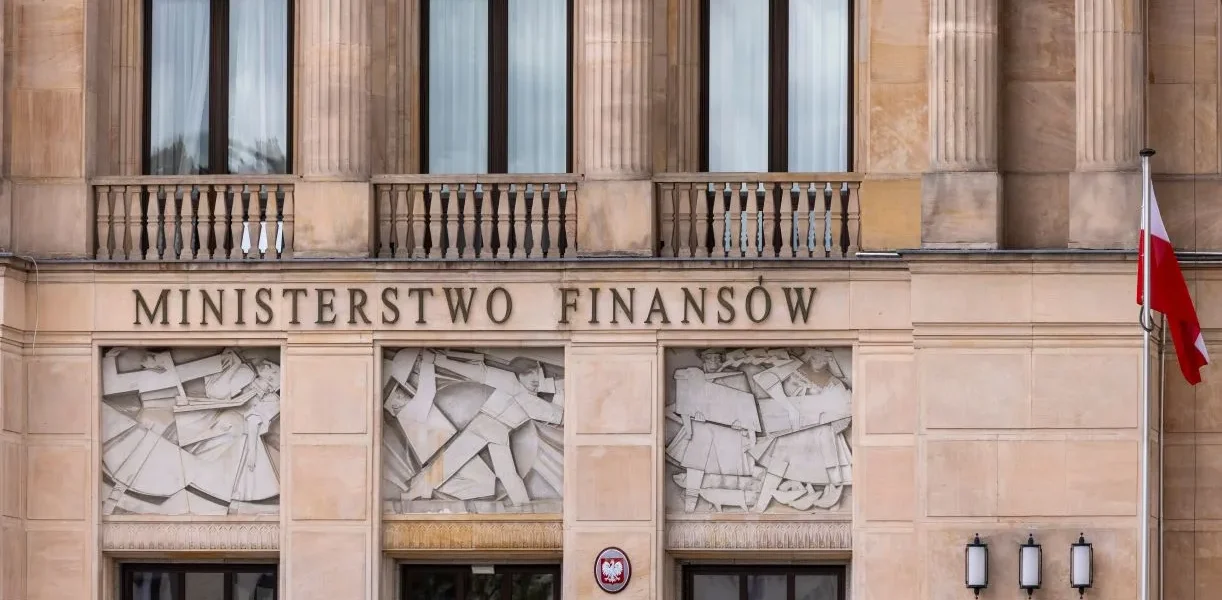
The Polish Ministry of Finance has introduced a bill amending PIT and CIT laws to curb the tax optimization and aggressive tax avoidance associated with family foundations. Crackdown on Tax...
The Polish Ministry of Finance has introduced a bill amending PIT and CIT laws to curb the tax optimization and aggressive tax avoidance associated with family foundations.
Table Of Content
Crackdown on Tax Optimization
The Ministry of Finance aims to limit the use of family foundations for tax optimization and income tax avoidance. The proposed changes are included in a bill amending the personal income tax and corporate income tax laws, published on Thursday at the Government Legislation Centre.
The ministry stated in the Regulatory Impact Assessment that market analysis revealed instances of family foundations being used contrary to their intended purpose. Specifically, authorities identified cases where foundations were established solely to secure tax advantages, such as deferred taxation, total tax exemption, or reduced rates.
Restrictions on Operational Activities and Asset Sales
The resort also identified situations where assets were contributed to a family foundation solely for subsequent sale under a preferential tax regime. Furthermore, the ministry highlighted the negative phenomenon of family foundations conducting operational activities through tax-transparent entities.
In these schemes, the foundation formally avoids conducting business directly while controlling or participating in entities that do, thereby circumventing the taxation of day-to-day business operations and engaging in aggressive tax optimization.
Proposed Tax Rate Increases and Structural Changes
The bill makes the application of preferential taxation contingent upon maintaining asset ownership for 36 months and eliminates the use of tax-transparent entities. Family foundations will also be covered by controlled foreign corporation regulations, while rules on real estate rental revenue will be clarified.
Additionally, the draft proposes raising the income tax rate on payouts from family foundations from 15 percent to 19 percent, while clarifying and tightening the catalog of hidden profits by expanding loan regulations and including written-off, time-barred, and uncollectible debts.
Incentives for Sibling-Founded Structures
The project introduces provisions designed to encourage siblings to establish family foundations. This includes personal income tax exemptions for benefits received by beneficiaries and individuals entitled to property upon the dissolution of a foundation who are descendants of the founders’ siblings.
This regulation fulfills the core purpose of ensuring intergenerational succession and preserving accumulated assets, applying rules analogous to those established when foundations are created by parents of siblings.